

EasyBudget - Budget planning analysis by Appwee
Managing a monthly budget sounds simple until everyday spending starts arriving from different places: a card payment here, cash there, a subscription you forgot about, and an unexpected bill that changes the whole month. I spent time with EasyBudget - Budget planning to see whether it makes that routine easier or merely gives it another screen to maintain. My impression is that it works best as a deliberately simple finance app for people who want a clear monthly spending plan without the weight of a full banking platform.
EasyBudget is a free finance app from Wallet Passes Alliance, with an Everyone age rating and support for Android 7.0 or later. It has been available since December 2, 2015, and the current version is 4.1.0. Its store presence is substantial enough to suggest that the straightforward approach appeals to many users: the app has over 500 thousand installs and an average rating of 4.0 from around 21 thousand ratings. Those figures do not make it automatically right for everyone, but they do place it among the more established simple budgeting choices rather than an unknown experiment.
Where EasyBudget users are most likely to get stuck
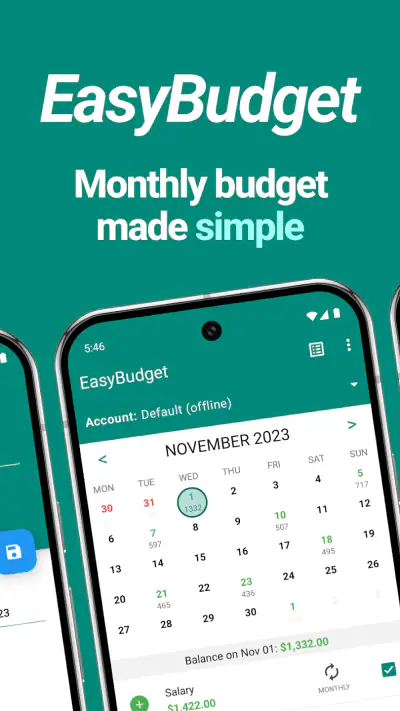
The first challenge is not learning a complicated feature set. It is deciding what the monthly plan should actually contain. A budget can become unhelpful when it includes every tiny purchase as a separate category, or when it is so broad that the numbers stop explaining anything. EasyBudget feels more useful when I treat it as a small set of spending boundaries rather than a complete financial archive.
For example, I would rather begin with categories such as groceries, transport, household bills, personal spending, and savings than create separate entries for coffee, lunch, snacks, and takeout on the first day. The point is to make the remaining amount understandable at a glance. If the category structure is too detailed, entering expenses becomes a chore and the habit is likely to disappear before the month is over.
Another common sticking point is confusing a budget with a record of money already spent. A monthly plan tells me what I intend to allocate; transactions tell me whether I am following that plan. If I enter a target and then forget to update spending, the app cannot reflect the real situation. That is not a flaw unique to EasyBudget, but its simple design makes the user’s consistency especially important.
I also found that the beginning of a month is not the only useful time to start. Someone who downloads the app halfway through a month may hesitate because the budget is already in progress. In practice, starting with the money still available and the bills still due can be more useful than trying to reconstruct every earlier purchase. A clean starting point usually produces better decisions than an incomplete history that looks precise but is not.
Use categories as decisions, not labels
The most effective setup is based on decisions I regularly make. “Food” can be sensible if I only need to know how much remains for eating. If groceries and restaurant spending compete for different reasons, splitting them makes sense. The test is simple: will seeing the category balance change what I do next? If not, it may not deserve its own place in the plan.
This is one of the app’s quiet strengths. EasyBudget does not force me into a complicated financial system before I understand my own habits. That makes it approachable for a first budget, but it also means the quality of the result depends heavily on the categories I choose. A thoughtful five-minute setup can be more valuable than a long list copied from a budgeting template.
A useful routine is to create the plan before the first ordinary spending day, then add unavoidable commitments before flexible spending. Rent, utilities, transport passes, and recurring obligations should shape what is available for discretionary categories. If I do this in reverse, the app may show a plan that looks comfortable until the fixed costs arrive.
Setup checks that prevent avoidable confusion
Before relying on EasyBudget, I would check that the monthly amount being planned is the amount I can genuinely use. That may be take-home income rather than a headline salary, and it should account for money already committed elsewhere. The app can help organize the plan, but it cannot decide which income figure is realistic for a particular household.
I would also check the starting point carefully. If I begin with an amount that includes money reserved for a bill, the available budget will appear larger than it really is. A practical approach is to list fixed obligations first, then divide what remains among flexible categories. This makes the app’s figures more useful because they represent spendable money rather than money that is merely sitting in the same account.
Another setup check is category naming. Similar names can create accidental fragmentation. “Travel,” “transport,” and “commuting” may overlap unless I define them before entering expenses. I prefer names that answer a clear question: how much can I spend on getting around, how much can I spend on food, and how much must remain untouched? That small bit of planning reduces later corrections.
Because EasyBudget is a budgeting tool rather than a replacement for a bank account, I would keep my bank or card records available during setup. The app is useful for planning and monitoring, but I should not assume that entering a budget automatically imports or verifies every real-world transaction. If a payment is missing from my own tracking, the budget can look healthier than my account balance.
A realistic month with the app
Imagine I receive my monthly income and immediately assign money to household bills, groceries, transport, and personal spending. During the first week, I buy groceries and pay for a train journey. Instead of waiting until the end of the month, I record those expenses while they are still easy to remember. The important result is not a perfect diary; it is knowing whether the remaining grocery amount can support the rest of the month.
In the second week, an unplanned repair appears. I would reduce a flexible category rather than quietly pretend the original plan still works. That is where a budgeting app becomes a decision tool. EasyBudget is most helpful when I use the updated figures to choose between delaying a purchase, moving money from another category, or accepting that the month will finish above plan.
At the end of the month, I would look for patterns rather than judge myself over one unusual expense. If personal spending repeatedly disappears early, the next month’s plan should reflect that reality or add a more specific category. If groceries vary widely, a single monthly limit may need a weekly checkpoint. These adjustments are more valuable than simply trying to make every month look neat.
Keep the first plan deliberately small
My strongest setup tip is to resist building a perfect budget immediately. Start with the categories that affect daily decisions, use the app through a normal week, and only then add detail where confusion remains. This reduces entry friction and reveals which parts of the plan are genuinely useful.
It is also worth deciding how often to review the budget. A quick check after a purchase is ideal when spending is easy to forget. A longer review once a week can work for someone who prefers batching. The trade-off is clear: batching saves interruptions but increases the chance of missing small expenses, while immediate entry improves awareness but requires more discipline.
Recovering when the workflow goes wrong
Every budgeting routine eventually falls behind. I might forget several purchases, enter an expense in the wrong category, or discover that the starting amount was incorrect. The worst response is abandoning the month because the figures are no longer perfect. A better recovery is to establish a new accurate point from the current balance and continue.
If I miss a few days, I would compare my bank or wallet records with the app and enter only the transactions I can identify confidently. For small cash purchases that I cannot reconstruct, I would make a reasonable adjustment to the relevant category rather than inventing a detailed list. The aim is to restore a useful picture, not create fictional precision.
When an expense is placed in the wrong category, correcting the category is preferable to changing the amount just to make a balance look better. Category accuracy matters because later decisions depend on what the money was actually used for. If a purchase genuinely belongs to two areas, I would use one consistent rule each time rather than changing the split from month to month.
If the monthly plan no longer matches reality, I would revise the plan openly. A budget is not a promise that circumstances cannot change. Moving money between categories can be sensible when a necessary cost rises, provided I understand which other goal is being reduced. EasyBudget is more useful when it reflects those choices than when I protect the original numbers at all costs.
What to do when the app seems not to update
When a figure looks wrong, I would first check the entry itself, the selected category, and the amount used for the current month. Many apparent app problems are actually caused by viewing a different period or forgetting that an expense was entered elsewhere. Closing and reopening the app, checking for the current version, and confirming that the device meets the Android 7.0 minimum are sensible general checks.
I would avoid repeatedly entering the same expense while trying to diagnose a balance. Duplicate entries can make recovery harder than the original problem. Instead, I would note the expected balance, inspect the recent entries carefully, and make one correction at a time. This slow approach is less frustrating and preserves a clear trail of what changed.
In-app purchases range from $0.99 to $99.99 per item, so I would review any purchase prompt before confirming it. The app is free to download, but “free” should not be treated as permission to approve an optional purchase without checking its purpose. For someone who only needs basic monthly planning, the free starting point may be enough; someone considering extra paid functionality should decide whether it solves a real problem in their routine.
When EasyBudget is not the cause of the problem
A budget can show uncomfortable numbers because the underlying spending is uncomfortable, not because the app is malfunctioning. If the remaining amount falls quickly, the first question should be whether the plan was too optimistic or whether fixed commitments were left out. Changing the app will not solve a mismatch between income and obligations.
The same applies when two people share expenses. If one person records purchases and the other does not, the budget will be incomplete. EasyBudget can still support a shared routine if both people agree on categories and timing, but it cannot create agreement by itself. For a household that needs synchronized accounts, automatic transaction imports, or detailed shared permissions, a more specialized financial service may be a better fit.
It may also be the wrong choice for users who want investment tracking, debt payoff calculations, tax preparation, or a full account register. EasyBudget’s appeal is its narrow focus on monthly planning. That focus keeps the experience less intimidating, but it also means I would not choose it as my only financial tool when the job requires advanced analysis or broad account management.
Compared with a spreadsheet, the app is easier to use casually because it is built around a budget routine rather than blank cells and formulas. A spreadsheet remains better for someone who enjoys customizing calculations, combining several accounts, or building long-term reports. Compared with a bank’s own spending screen, EasyBudget can be more intentional because I set the categories and limits myself, while a bank view may be better for verified transaction history.
Compared with feature-heavy budgeting platforms, EasyBudget is less demanding to learn and less likely to overwhelm a beginner. The trade-off is that users who expect automatic synchronization, extensive charts, or detailed financial forecasting may find the simpler workflow restrictive. I see that as a deliberate boundary rather than a hidden advantage: it is good at helping me plan a month, not at becoming a complete personal finance command center.
Who will get the most from it
I would recommend EasyBudget to someone who wants to stop guessing where the monthly money went, especially if they are comfortable entering expenses manually and prefer a clean starting point. It also suits users who are trying budgeting for the first time and need a manageable routine rather than a technical project.
It can be useful for a student, a new worker, or anyone whose income and expenses are fairly understandable from month to month. It may also help someone who already knows their financial situation but needs a visible limit for flexible spending. The app’s Everyone rating makes it broadly accessible, although the right choice still depends on the user’s financial complexity and willingness to maintain the entries.
I would skip it if I know I will not record spending, if my finances involve many accounts that need automatic consolidation, or if I need sophisticated planning beyond a monthly budget. In those cases, a spreadsheet or a more advanced finance platform may justify its extra complexity. Choosing a simpler app is only helpful when its simplicity matches the job.
My practical verdict after using it
EasyBudget succeeds by keeping the central question visible: what can I spend this month, and what will happen if I do? I like that it does not require a beginner to understand a large financial system before taking the first step. Its strongest value comes from regular, honest updates and sensible categories, not from treating the app as a passive dashboard.
The main friction is equally clear. Manual budgeting asks for attention, and an inaccurate starting plan can make the rest of the month misleading. Users who want their finances to update automatically may become frustrated, while users willing to make a brief habit of recording expenses can get a practical view of their choices. The app works best as a decision aid, not as a substitute for checking your real accounts.
Wallet Passes Alliance has kept the product focused on approachable monthly planning, and the established install base shows that this straightforward idea has found an audience. The 4.0 average is a reasonable reflection of that balance: strong enough to show broad usefulness, but not a reason to ignore the limitations of a simple tool.
My recommendation is to try it with one uncomplicated month, five or fewer meaningful categories, and a fixed review routine. Do not judge it after entering a theoretical budget and never looking again. Use it when a purchase decision is still changeable, correct mistakes without chasing perfection, and compare its remaining amounts with your actual account balance. If that rhythm helps you make calmer choices, EasyBudget is a worthwhile free finance companion. If you need automation, shared account management, or advanced financial modeling, its simplicity will probably feel like a ceiling rather than a benefit.
For a person asking whether a monthly budget can be made less intimidating, my answer is yes, with one condition: the app can organize the plan, but I still have to keep the plan alive. That is a fair trade for a focused tool, and in the right hands, EasyBudget is a practical place to begin building that habit.
Gallery
EasyBudget - Budget planning Pros and Cons
- Simple interface makes daily expense tracking quick and approachable.
- Flexible categories help organize spending around personal priorities.
- Budget progress gives a clear view of remaining funds during the month.
- Useful for building consistent saving and spending habits over time.
- Lightweight design should run smoothly on most modern Android and iOS devices.
- Manual transaction entry can become tedious for frequent purchases.
- Limited automation may require more effort than full-featured finance apps.
- Advanced reports and investment tracking may not be available.
- Budget accuracy depends on remembering to record every transaction.
- Users may want stronger customization for currencies
- categories
- or recurring bills.
EasyBudget - Budget planning Frequently Asked Questions
What is EasyBudget - Budget planning, and who is it designed for?
EasyBudget - Budget planning is a personal finance app designed to help users organize income, expenses, budgets, and everyday spending in one place. It can be useful for beginners who want a simple overview of their money, as well as more experienced users who need a convenient way to monitor categories, plan upcoming costs, and understand their spending habits without relying on complicated spreadsheets.
Can I use EasyBudget to track expenses and create a realistic budget?
Yes, the app is intended for recording daily expenses and organizing them into spending categories, making it easier to compare actual purchases with your planned budget. Before downloading, keep in mind that the usefulness of the results depends on entering transactions consistently and accurately. It is best suited to users who are willing to update their records regularly rather than expecting completely automatic financial management.
Does EasyBudget - Budget planning connect to my bank accounts automatically?
Users should check the current app description and permissions before assuming that bank synchronization is available. Many budgeting apps focus on manual entry, while others may offer account connections depending on the platform, country, or subscription plan. If EasyBudget requires manual transaction input, this can provide greater control and privacy, but it also means that balances may not reflect reality unless purchases and income are entered promptly.
Is my financial information safe when using EasyBudget?
Because budgeting apps may contain sensitive details about income, purchases, and financial habits, users should review EasyBudget’s privacy policy, requested permissions, and data-storage practices before adding personal information. Avoid entering banking passwords, card security codes, or other credentials unless the app clearly explains why they are needed and how they are protected. Keeping your device secured with a passcode also adds an important layer of protection.
Is EasyBudget - Budget planning free, and are there any limitations?
The app may be available to download at no initial cost, but some features can depend on the version, operating system, region, or optional in-app purchases. Before installing, review the store listing for advertising, premium tools, subscription terms, export options, and possible limits on budgets or categories. Checking these details in advance helps you understand whether the free version provides everything you need for regular financial planning.














